

Insurance regulators across East Africa are moving to standardise the way
insurance companies are supervised, in a push to make it easier to compare
underwriting practices and strengthen oversight of the region’s growing
insurance market.
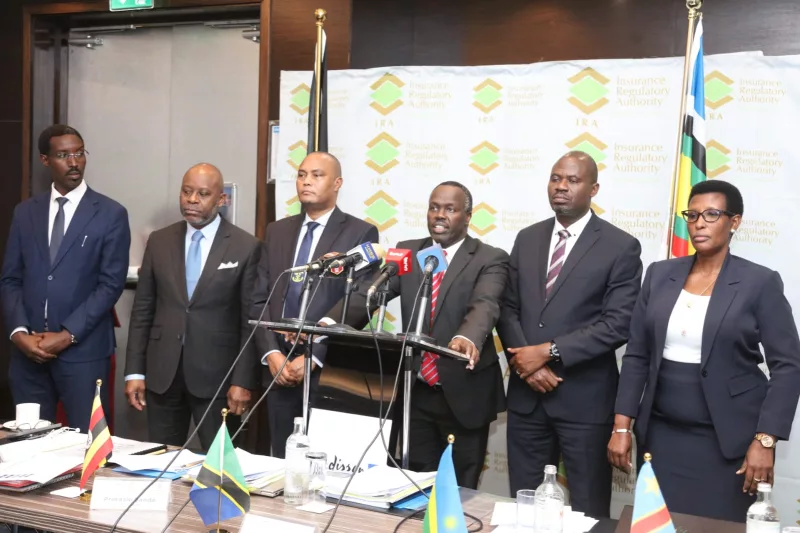
The move was agreed by commissioners and insurance supervisors from several
East African countries during a two-day meeting held under the East African
Association of Insurance Supervisors (EASA).
The regulators agreed to harmonise the template used to assess compliance
with insurance core principles, creating a common basis for evaluating insurers
across the region.
Insurance provision is guided by 25 insurance core principles, but
regulators have been assessing compliance differently in their respective
countries.
The associations chair Protazio Sande, said the harmonised approach would
allow regulators to assess individual markets while also comparing their
performance with regional peers.
“We have agreed to harmonise a template so that we can do assessment at
country level, but also compare with our peers. The standardisation is expected
to strengthen supervisory consistency as insurers increasingly operate across
borders and take on more complex risks,” said Sande.
The regulators also agreed to develop a regional integrated insurance
supervisory software that would allow them to access and exchange information
in real time.
They argue that increasing digitisation of insurance had made traditional
methods of collecting information from individual market players less
effective.
“For us to be in charge and do effective supervision, we need to be enabled
by a software. The proposed system will allow supervisors to use the same
platform while sharing information and comparing developments across markets,”
he said.
The regulators are also seeking to harmonise digital transformation
practices in the insurance sector. Countries in the region are at different
stages of digitisation, with some having advanced practices in areas such as
distribution and mobile-based insurance services.
The regulators want to document these practices and share them across the
region to help markets adopt approaches that can improve access to insurance.
The push for common oversight comes as East African insurers face growing
demand to cover larger and more complex risks, including those arising from
mining, oil and gas and other emerging economic activities.
Regulators said insurance companies are increasingly required to hold
capital in line with the risks they underwrite, rather than relying solely on
minimum capital requirements.
Under the risk-based capital approach, insurers face additional capital
charges depending on the risks they take on. Companies seeking to underwrite
larger risks may therefore have to raise additional funds from shareholders.
The regulators also pointed to mergers and acquisitions in the region as
evidence of insurers seeking to become stronger and increase their capacity to
absorb emerging risks.
Despite concerns over the ability of local insurers to handle large risks,
regulators said the region has capacity to underwrite significant risks, with
international reinsurance markets available where local capacity is
insufficient.
The regional supervisors also agreed to establish a common
complaints-management framework to improve policyholder protection.
The framework is intended to ensure that consumers receive broadly similar
standards when resolving insurance complaints regardless of whether they
purchased cover in Kenya, Tanzania, Rwanda, Uganda or Burundi.
The regulators are further working on a unified constitution for EASA and a
governance charter to provide a common institutional framework for the
association.
Sande said the various resolutions were expected to make significant
progress within one year, although the adoption of the common constitution
could take longer because countries have different legal procedures.
The regulators said stronger coordination would ultimately support the
development of East Africa’s insurance markets by improving supervisory
effectiveness, sharing information and creating more consistent standards for
insurers operating in the region.