

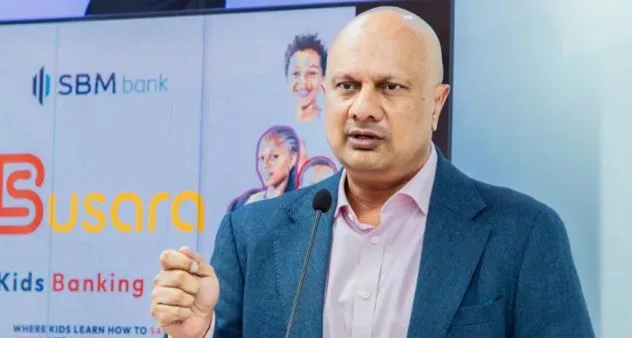
SBM Bank Kenya chief executive Bhartesh Shah/ HANDOUT
SBM Bank Kenya has reported a 122
per cent increase in profit before tax to Sh911 million for the nine months
ended September 2026, retaining growth after a two-year loss streak.
The subsidiary
of Mauritius-based SBM Group, accumulated significant financial
pressures following its entry into the Kenyan market in 2017 (via Fidelity
Commercial Bank acquisition) and 2018 (via Chase Bank assets), culminating in a
heavy multi-year period of losses, before a turnaround in December last year.
The lender’s pre-tax profit rose
from Sh411 million recorded in the corresponding period last year, reflecting
progress in diversifying revenue streams and strengthening relationships with
retail and business customers.
Operating profit nearly tripled to
Sh1.3 billion from Sh447 million a year earlier, while total income increased
33 per cent to Sh5.44 billion.
Net interest income during the
period under review grew 29 per cent to Sh3.44 billion, while non-funded income
rose 39 per cent to Sh2 billion, supported by increased customer transactions
and trade finance activities.
Transactional income surged 95 per
cent, while trade finance commissions grew 98 per cent, highlighting the bank’s
efforts to expand services beyond traditional lending.
Operating costs increased 12 per
cent, slower than the growth in income, helping to strengthen profitability
during the period.
Customer deposits rose 29 per cent
year-on-year to Sh97.3 billion as of September 30, reflecting increased
customer balances and providing a larger funding base for lending.
Net loans and advances grew 23 per
cent to Sh56.5 billion, signalling an expansion in the bank’s lending
activities to households and businesses.
SBM Bank Kenya chief executive,
Bhartesh Shah, yesterday said the results reflected investments in systems,
stronger credit discipline and efforts to deepen customer relationships.
“Strong institutions are built
through decisions that reinforce one another over time. We have focused on
strengthening our systems, improving credit discipline and earning a larger
place in our customers’ everyday lives,” Shah said.
The bank also reported an
improvement in asset quality, with its non-performing loan (NPL) ratio
declining to 16.9 per cent in September from 32.3 per cent a year earlier and
17.3 per cent in June.
The reduction represents a 15.4
percentage-point improvement over the year, reflecting efforts to address its
legacy loan book and tighten credit management.
However, the lender recorded a net
impairment charge of Sh418 million during the nine-month period as it continued
provisioning for potential credit losses and recognising risks in its loan
portfolio.
Shah said loans underwritten since
he took office in May 2024 had an NPL ratio of one per cent, offering an
indication of the performance of more recently originated loans.
The bank has also completed an upgrade
of its core banking system. It is now focusing on improving service turnaround
times, productivity and consistency in credit decisions.
Digital banking remains another
priority, with the lender advancing mobile banking, digital onboarding, its
Busara loyalty programme and zero-fee PesaLink transfers.
The next phase will focus on
increasing customer adoption, usage and service reliability as the bank seeks
to sustain growth while maintaining prudent lending standards.